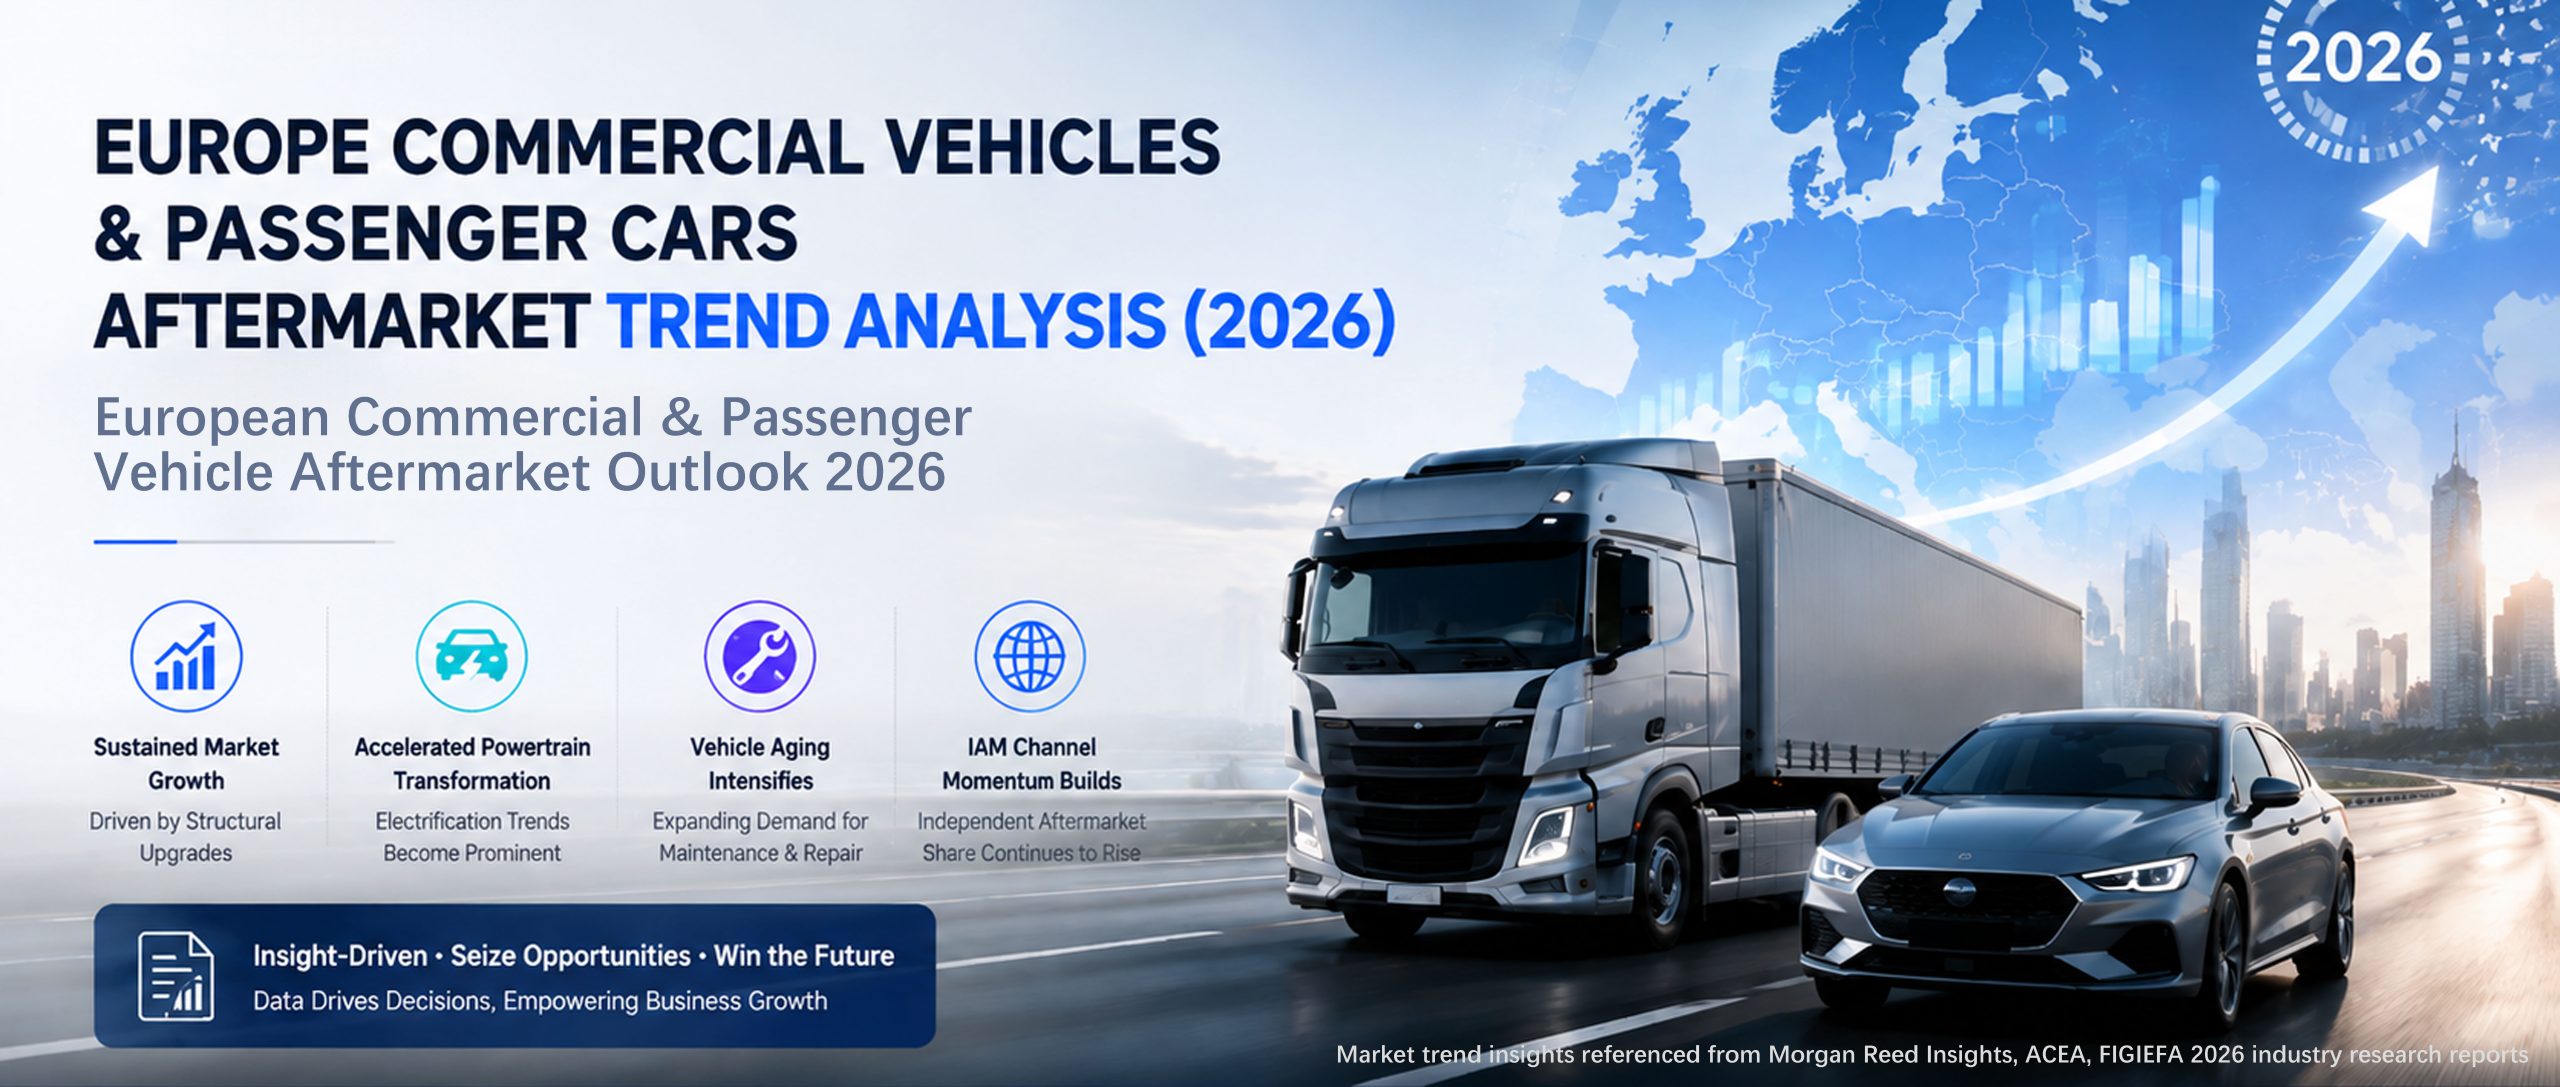
Europe is one of the world’s most mature automotive markets, and its aftermarket has long served as a key benchmark for global automotive aftermarket trends. By 2026, Europe’s vehicle parc is estimated at approximately 300 million units, with passenger vehicles accounting for around 88% and commercial vehicles approximately 12% [Note 1]. As the average age of vehicles continues to rise, electrification accelerates, and geopolitical developments reshape supply chains, the European aftermarket is undergoing significant structural changes.
This article examines the European aftermarket across the commercial and passenger vehicle segments, with a focus on three key dimensions: market demand, product evolution, and channel dynamics. Particular attention is given to the changing demand for thermal management and heat exchange components, as well as the emerging opportunities created by vehicle electrification.
1. Commercial Vehicle Aftermarket: Demand Driven by Vehicle Uptime
1.1 Market Size and Fleet Characteristics
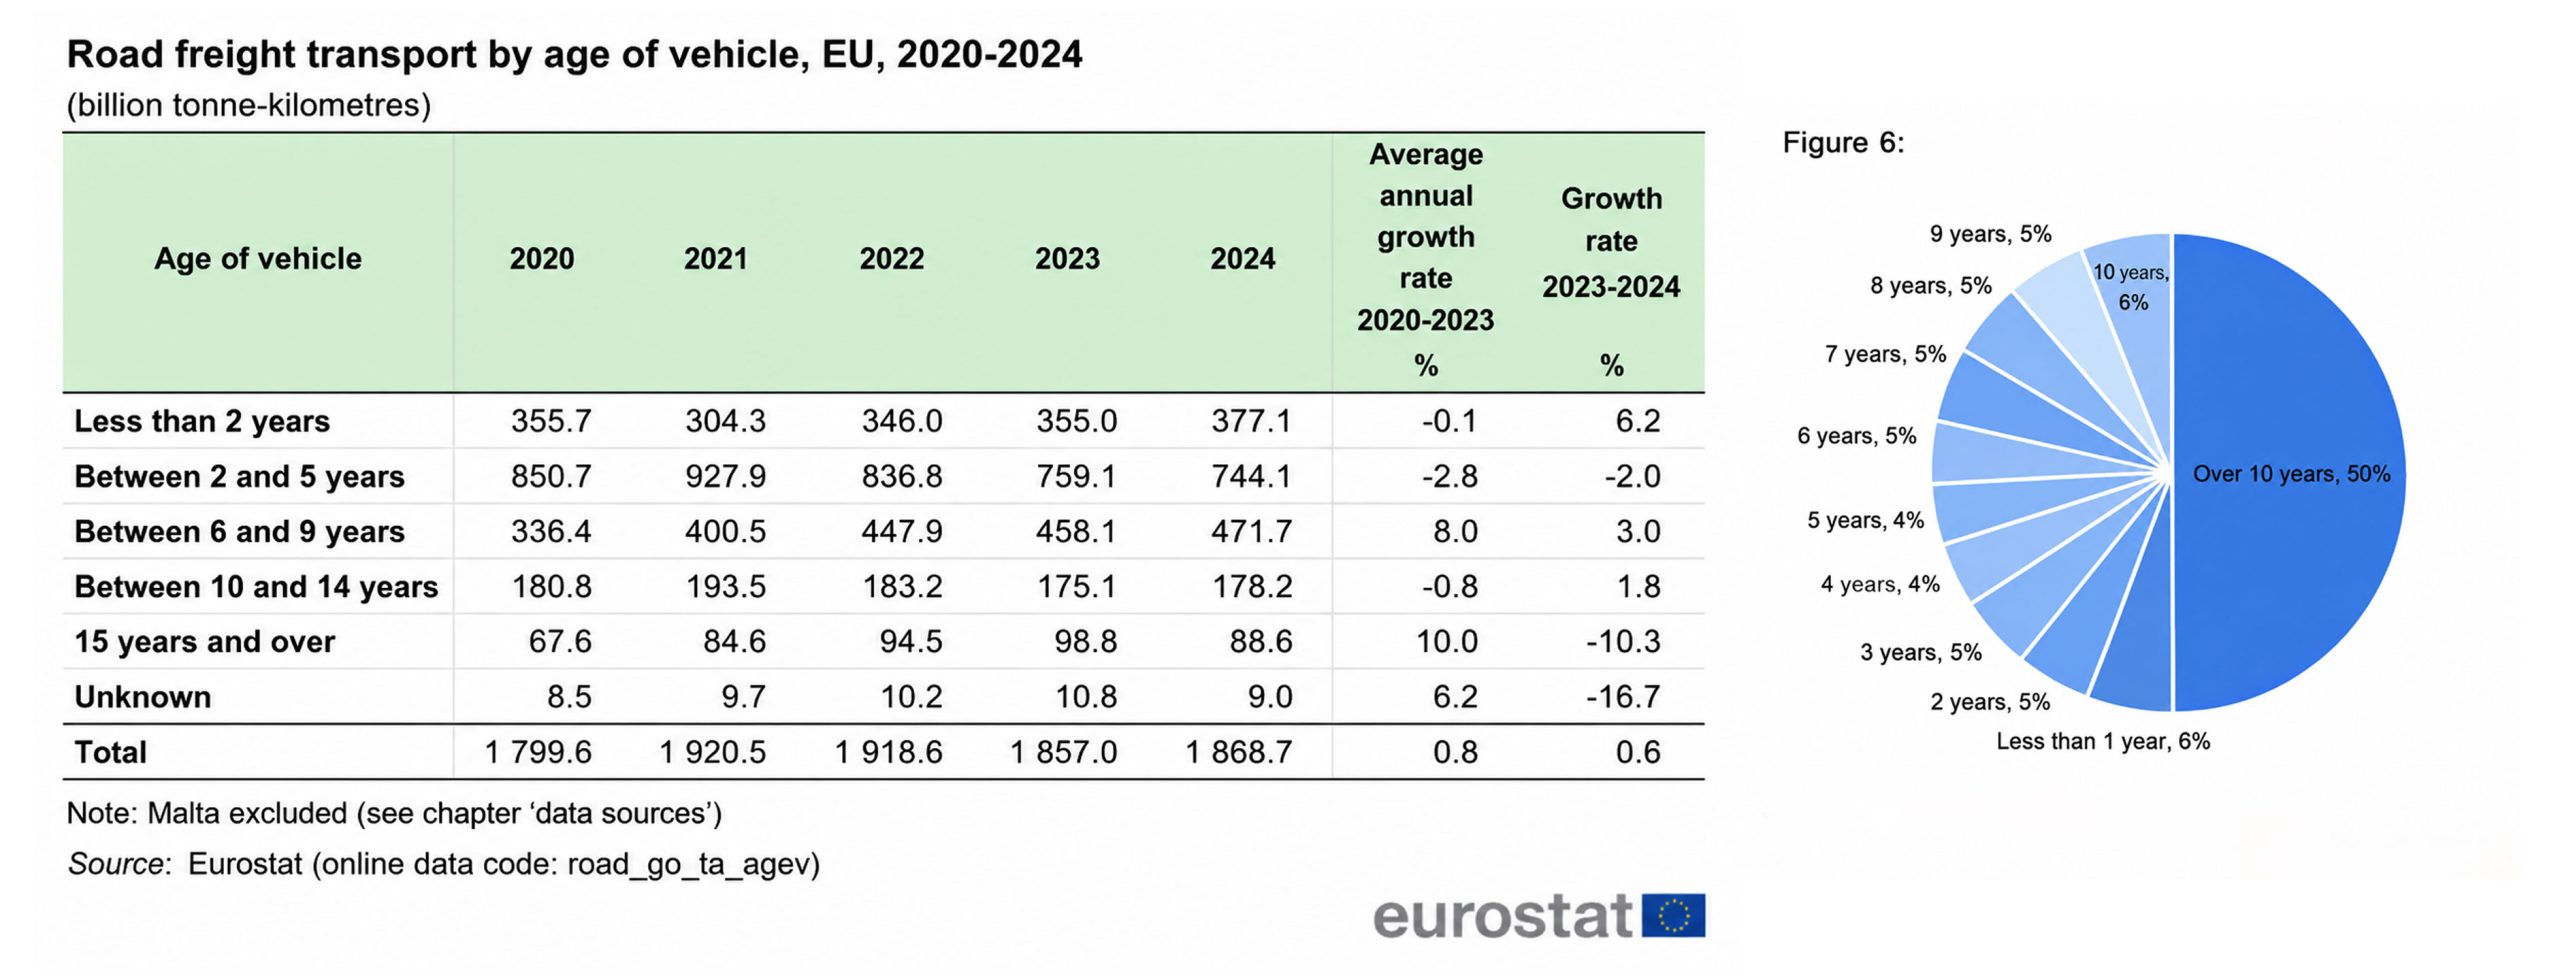
Europe’s commercial vehicle parc is estimated at approximately 36 million units,[Note 2] covering light commercial vehicles, medium-duty trucks, heavy-duty trucks, and buses/coaches.
Heavy-duty trucks account for only around 18% of the total commercial vehicle fleet, yet they handle more than 75% of Europe’s road freight transport volume. This makes the heavy-duty segment one of the most valuable areas of the commercial vehicle aftermarket.
Fleet age is also becoming an increasingly important market driver. According to data from the European Automobile Manufacturers’ Association (ACEA), the average age of heavy-duty trucks in Europe has continued to rise over the past decade and now exceeds 13 years.[Note 3] Longer fleet service lives are directly driving sustained demand for maintenance, repair, and replacement parts.
1.2 Key Demand Drivers
Vehicle Uptime Remains the Top Priority
Commercial vehicles are productive assets, and downtime directly translates into lost revenue.
Vehicles operated by European logistics companies typically accumulate between 120,000 and 150,000 kilometers per year, while some long-haul fleets exceed 200,000 kilometers annually. Under these intensive operating conditions, preventive replacement intervals for cooling system components—including radiators, condensers, intercoolers, and other heat exchange products—are significantly shortened.
As a result, thermal management components remain among the most frequently replaced product categories in the commercial vehicle aftermarket.
Stricter Emissions Regulations Are Driving Technology Upgrades
The Euro 7 emissions standard completed the legislative process and entered into force in 2025. Implementation for new vehicle types and newly registered vehicles will be phased according to vehicle category, beginning in 2026/2027 for passenger cars and vans and in 2027/2028 for buses and heavy-duty trucks.[Note 4]
The new requirements place greater emphasis on thermal management performance, including heat transfer efficiency and corrosion resistance, raising the technical standards expected of related components and systems.
Fleet Life Extension Before Vehicle Replacement
Rising new vehicle prices and uncertainty surrounding the pace of electrification are encouraging many small and medium-sized logistics operators in Europe to extend the service life of their existing fleets.
Against this backdrop, replacing critical components such as radiators has become an increasingly important way to extend vehicle service life and maintain fleet operating efficiency before full fleet replacement.
2. Passenger Vehicle Aftermarket: Two Parallel Demand Drivers
2.1 The Existing Fleet: Vehicle Aging Sustains Replacement Demand
The average age of passenger vehicles in Europe continues to increase. According to ACEA data, the average age reached 12.3 years in 2023 and has risen to more than 13 years by 2026.[Note 5] Major markets including Germany, France, and Italy are all operating with historically mature vehicle fleets, with average vehicle ages of approximately 12, 13, and 13.5 years respectively.
For aging vehicles, thermal management systems are increasingly affected by declining heat transfer efficiency, deteriorating seals at pipe connections, and internal corrosion and blockage. These problems tend to become more pronounced once vehicles exceed ten years of service, driving replacement demand for radiators, heater cores, condensers, and related components toward its peak.
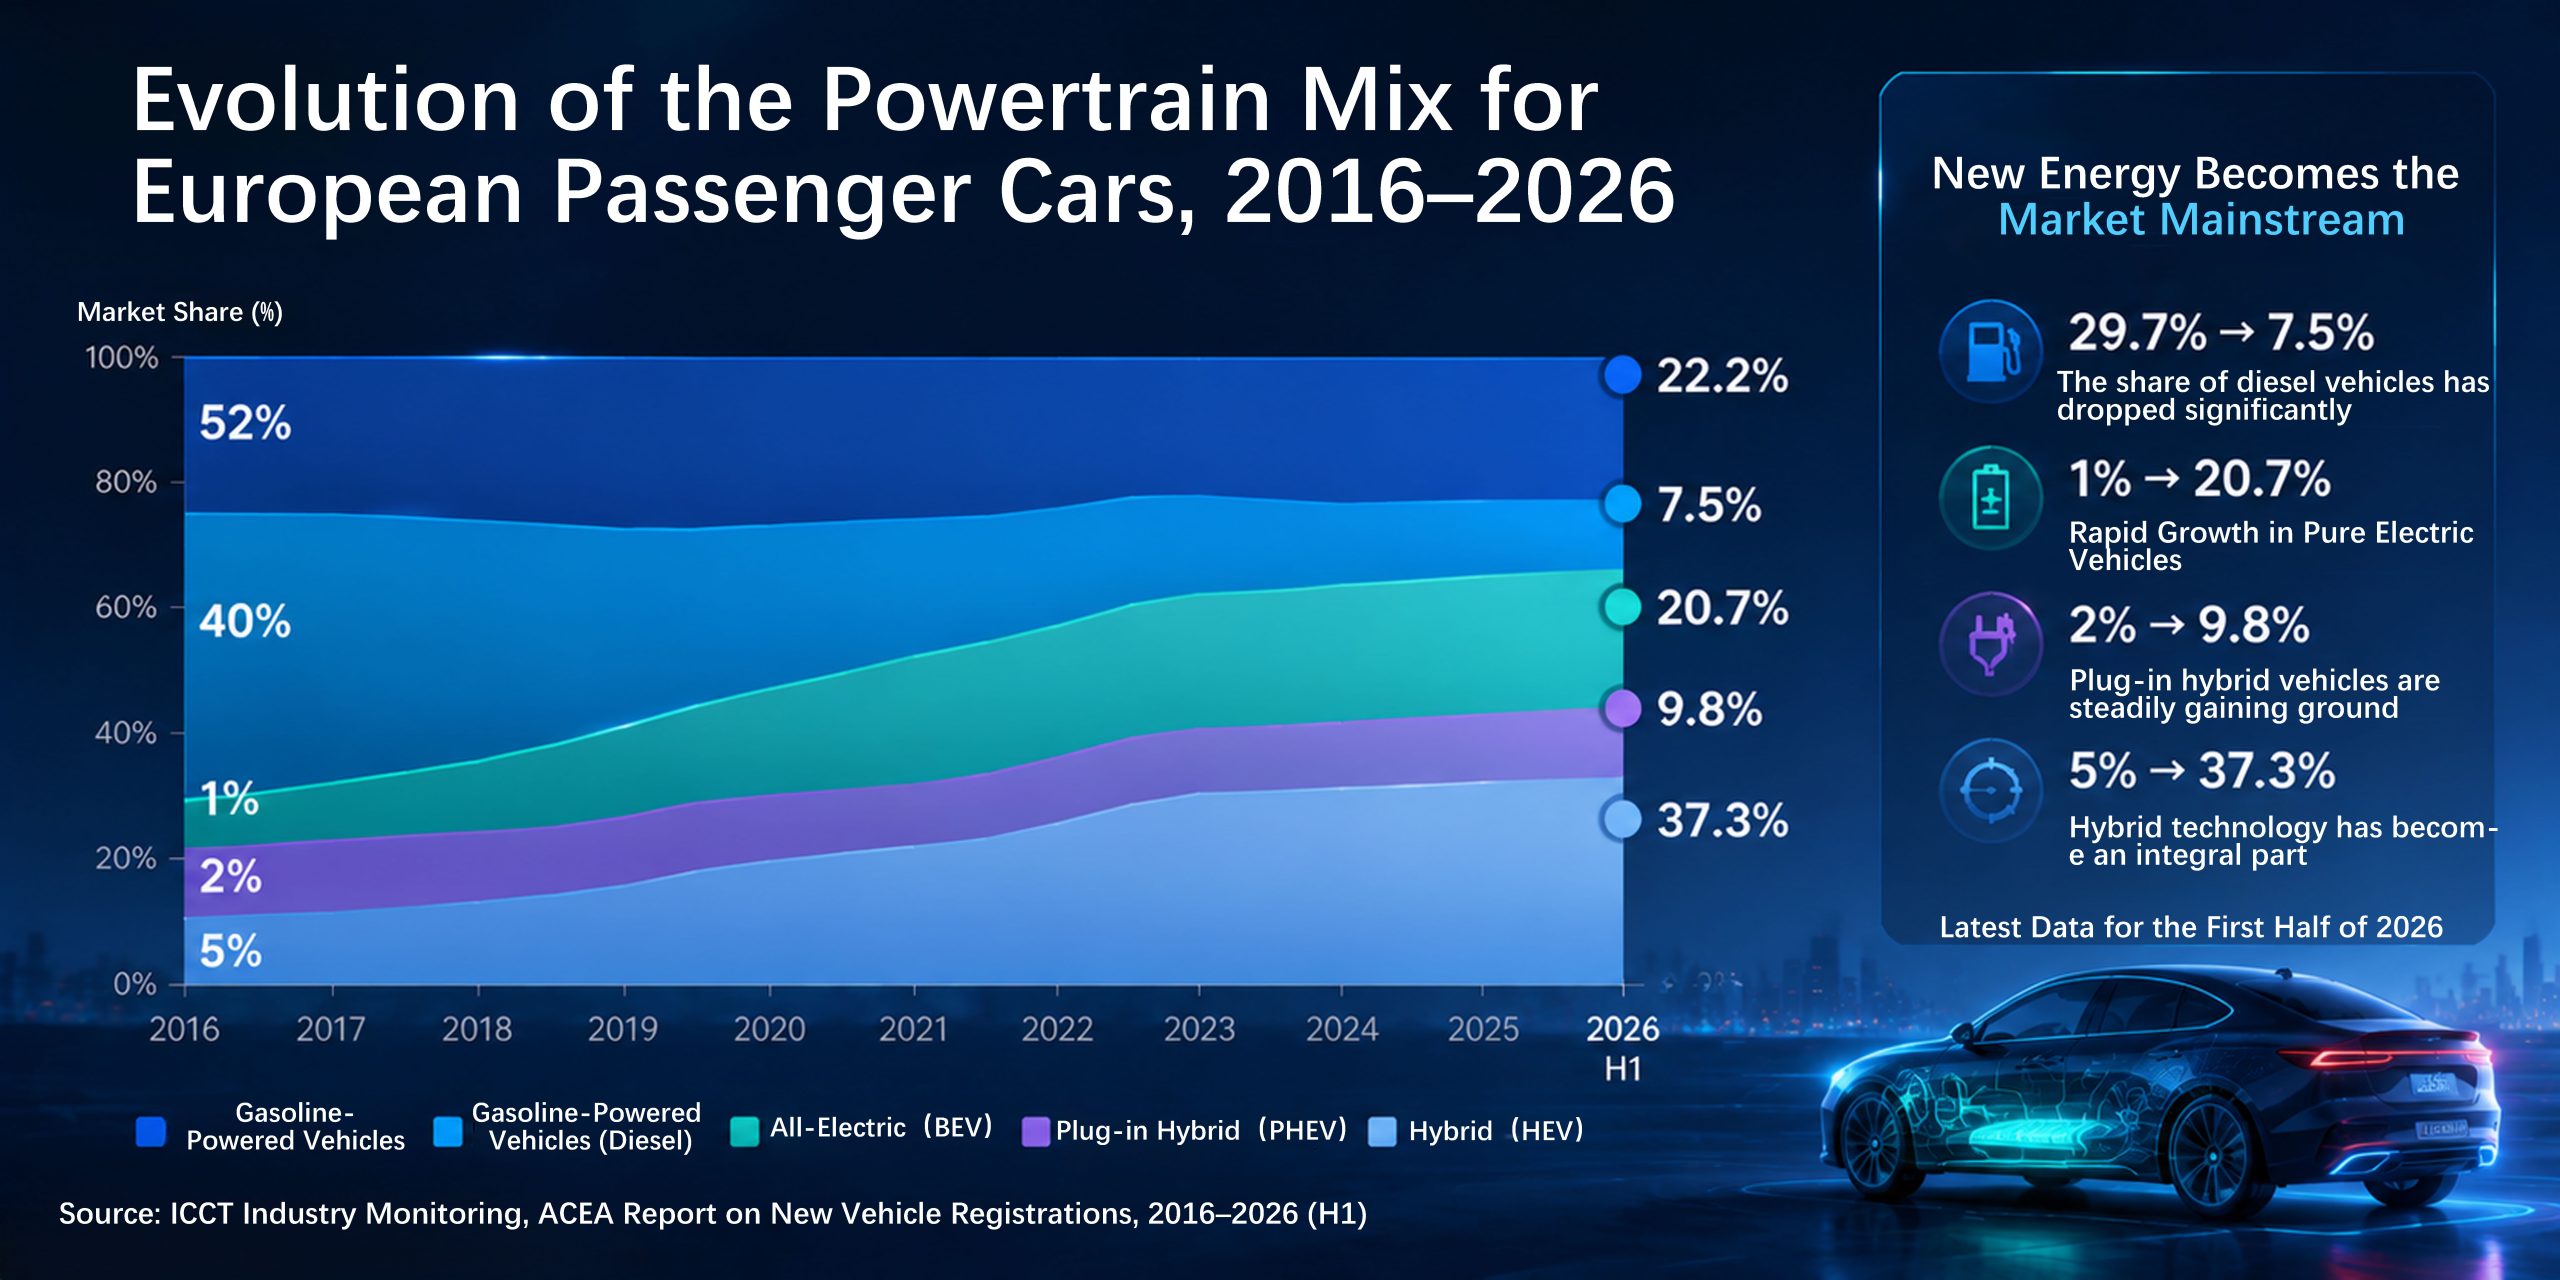
The powertrain mix is also reshaping aftermarket demand. Diesel vehicles accounted for approximately 52% of Europe’s passenger vehicle fleet in 2015, but that share has fallen significantly to below 30% in recent years.[Note 6] Meanwhile, gasoline and hybrid vehicles have gained market share.
Different powertrain technologies require different thermal management specifications, creating new challenges for suppliers in terms of product range, application coverage, and technical adaptability.
2.2 The Emerging Market: Electrification Creates a New Thermal Management Opportunity
According to data from the European Automobile Manufacturers’ Association and industry monthly sales reports, battery electric vehicles (BEVs) accounted for nearly 30% of new vehicle sales in Europe during the first half of 2026, while plug-in hybrid electric vehicles (PHEVs) represented approximately 10%.[Note 7] Combined, new energy vehicles accounted for more than one-third of new vehicle sales.
The thermal management architecture of electric vehicles differs fundamentally from that of conventional internal combustion engine vehicles.
Battery Thermal Management
Traction batteries need to operate within an optimal temperature range of approximately 20°C to 40°C. Excessive heat or cold can affect battery life and safety, making dedicated battery cooling and heating systems an increasingly important component of EV thermal management.
Electric Drive System Cooling
Electric motors and inverters generate substantial heat during operation and require dedicated liquid-cooling circuits to maintain stable performance and reliability.
The Transformation of HVAC Systems
Unlike conventional vehicles, electric vehicles cannot rely on engine waste heat for cabin heating. Heat pump HVAC systems have therefore become an important technology pathway, significantly changing the design requirements for condensers, evaporators, and related thermal management components.
Large-scale aftermarket demand for electric vehicles has not yet been fully released. The average age of EVs currently on the road is only around four to five years, and most vehicles remain within their original manufacturer warranty period.
However, the significantly greater complexity of EV thermal management systems means that, over the medium and long term, this segment is expected to become an important growth engine for the automotive aftermarket.
3. Channel Dynamics and Supply Chain Developments
3.1 Independent Aftermarket Channels Continue to Expand
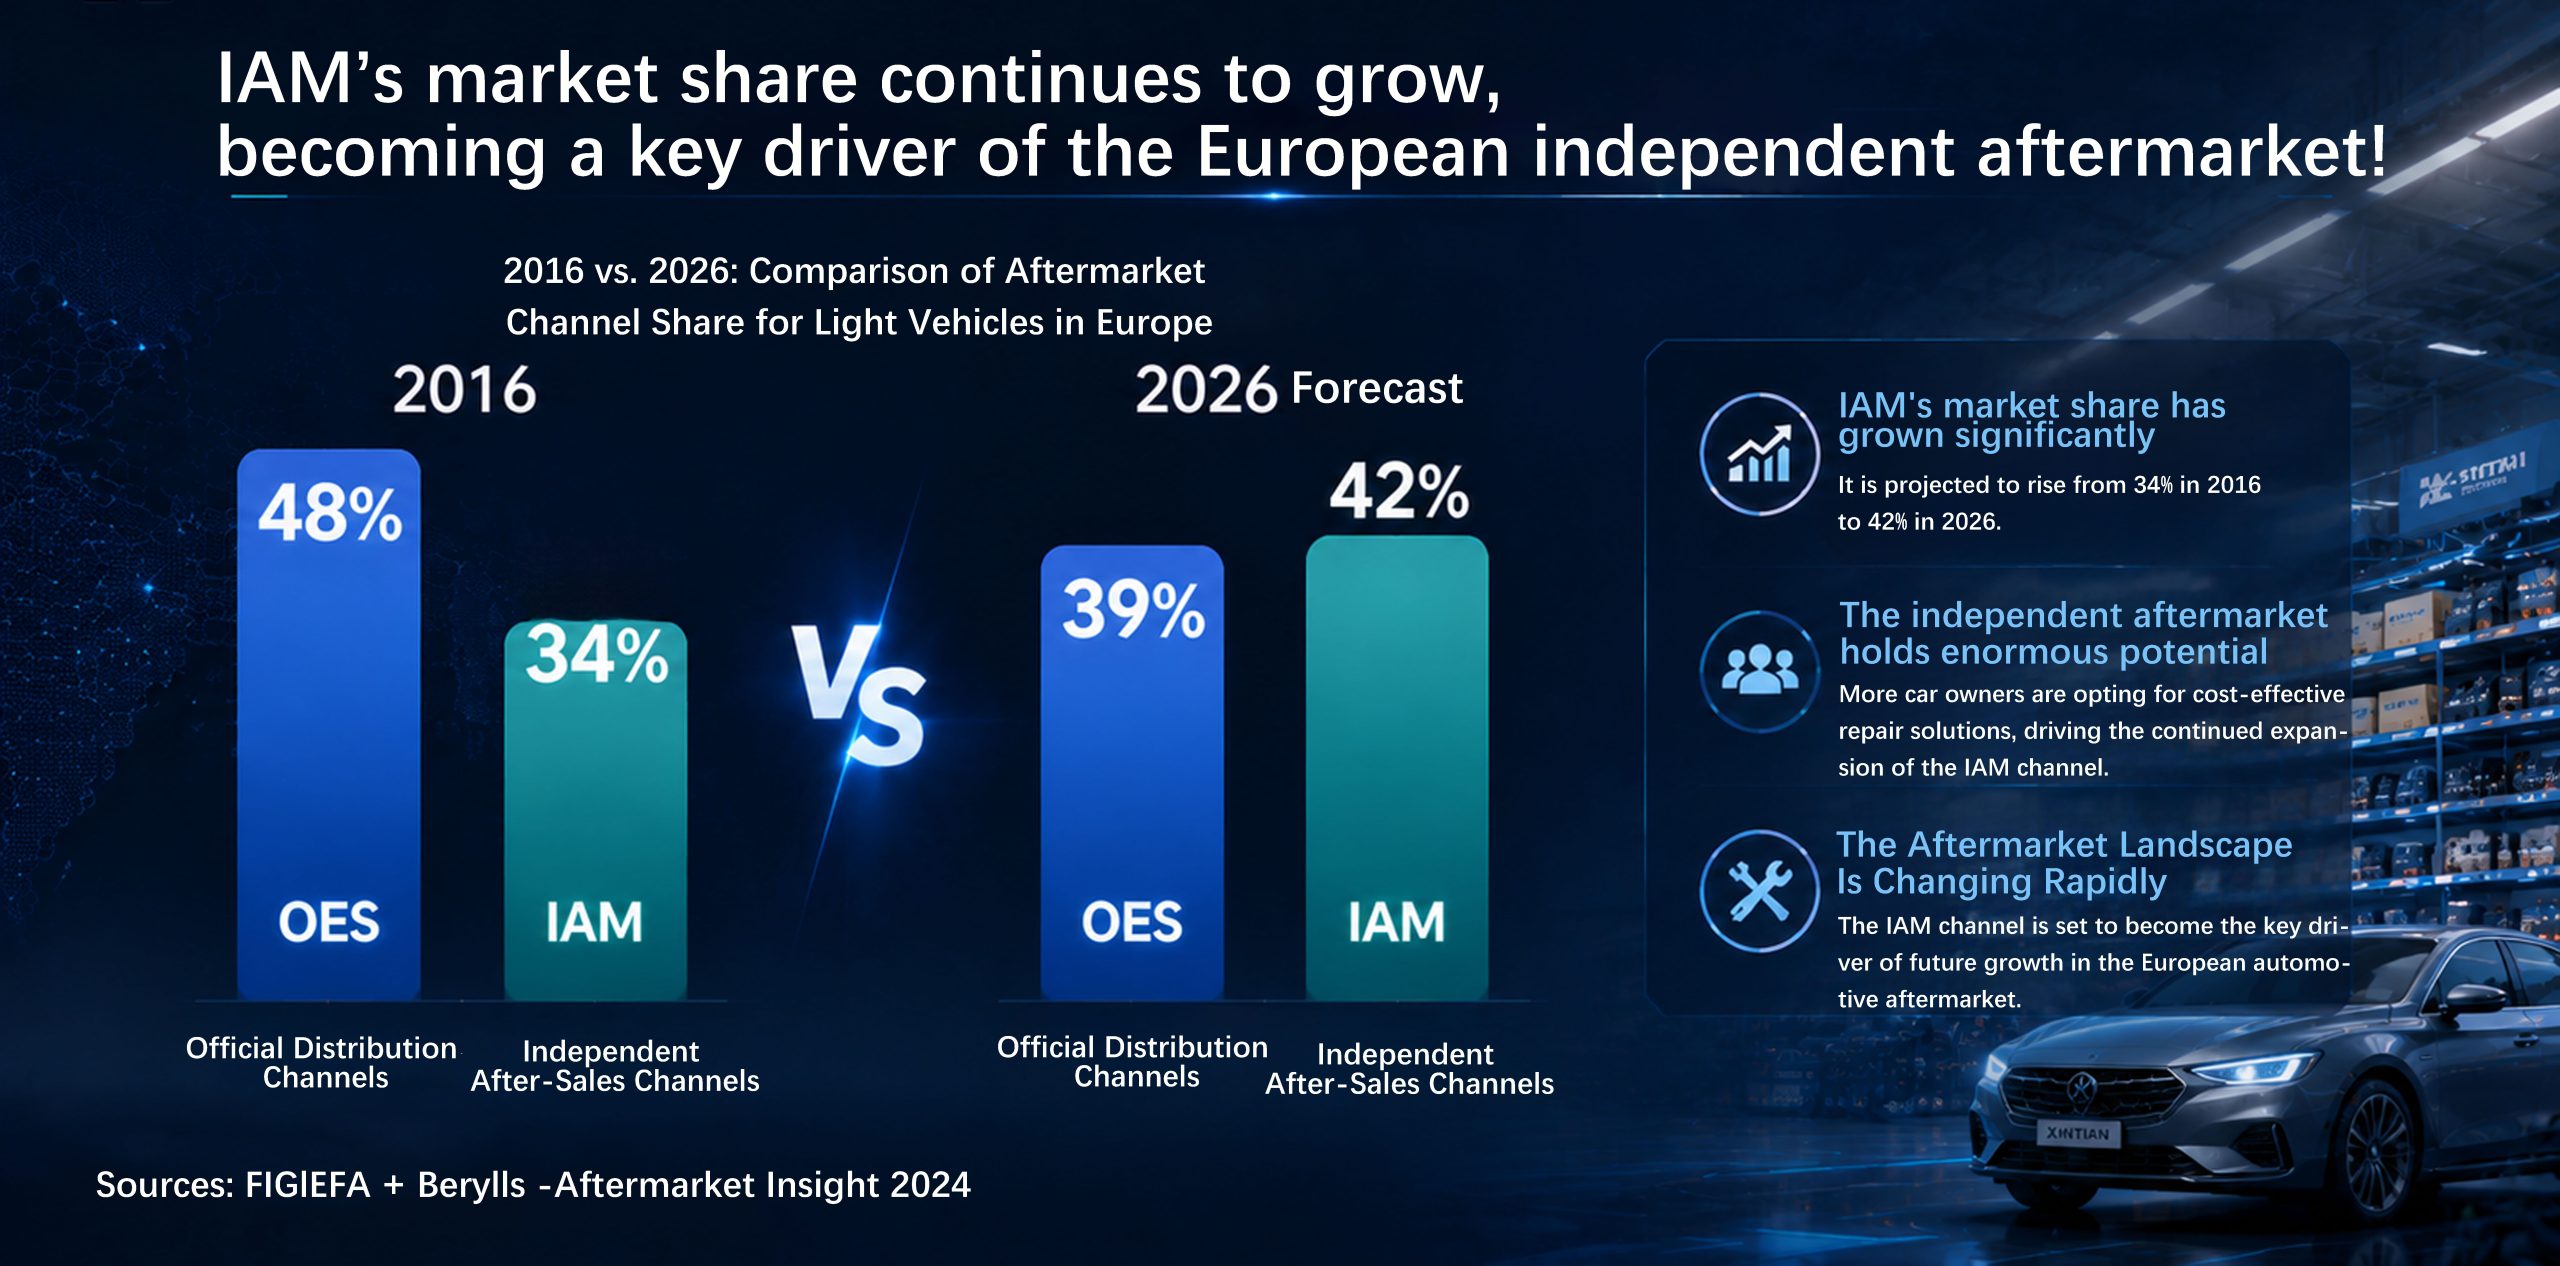
The European automotive aftermarket can broadly be divided into Original Equipment Service (OES) and Independent Aftermarket (IAM) channels.
Over the past decade, the IAM channel has steadily expanded its market share and now accounts for more than 60% of the European aftermarket.[Note 8]
Key drivers include regulatory protection for aftermarket competition within the European Union, improvements in the quality of independent replacement parts, and growing consumer demand for cost-effective vehicle repair and maintenance.
For international suppliers whose primary route to market is the independent aftermarket, this structural shift is broadly favorable.
3.2 Supply Chains Are Becoming Increasingly Regionalized
Geopolitical developments are reshaping the supply chain landscape for automotive parts entering the European market.
Eastern European countries such as Poland, Romania, and Türkiye, together with North African markets including Morocco and Tunisia, are strengthening their positions as nearshore supply bases for Europe. Meanwhile, the share of supply originating from East Asia has fluctuated across certain product categories.
In the heat exchanger sector, Chinese suppliers continue to hold a significant position in the European market, supported by mature industrial clusters and strong cost competitiveness. At the same time, competition from localized production is increasing.
Chinese companies with overseas manufacturing capacity and international production footprints are therefore better positioned to respond to the ongoing restructuring of automotive supply chains.
4. Product Trends in Thermal Management and Heat Exchange Systems
4.1 Radiators
Demand for automotive radiators in Europe continues to grow steadily, with annual market value estimated by industry research organizations to range from several hundred million to more than one billion euros.[Note 9]
Demand is somewhat stronger in the commercial vehicle segment than in the passenger vehicle segment, primarily due to higher vehicle utilization and shorter replacement cycles.
From a product perspective, all-aluminum radiators continue to gain market penetration, while copper-brass radiators remain primarily relevant to repair applications involving older vehicle models.
4.2 Condensers
The increasing frequency of extreme summer temperatures across Europe is placing greater loads on vehicle air conditioning systems, increasing the likelihood of condenser aging and failure.
At the same time, the growing adoption of heat pump HVAC systems in electric vehicles is driving updates to condenser specifications and designs. Microchannel condensers are consequently gaining a larger share of the market.
4.3 Heater Cores
As a core component of vehicle cabin heating systems, heater core replacement demand is closely linked to vehicle age.
Europe currently has approximately 80 million passenger vehicles that are more than 12 years old, representing a substantial potential replacement market for heater cores.
This is a mature product category, with differentiation primarily focused on corrosion protection technologies and sealing structure design.
4.4 Intercoolers
Intercoolers are critical components of turbocharged engine intake systems. They cool compressed, high-temperature intake air to increase charge density and improve engine performance.
Europe’s high penetration of diesel turbocharging technology continues to support stable replacement demand for intercoolers. In the commercial vehicle segment, intercoolers are a high-frequency replacement category.
Heavy-duty trucks are exposed to sustained boost pressure and repeated thermal cycling over long operating periods. Core fatigue cracking and fin corrosion or blockage are among the primary failure modes and typically become more prevalent once vehicle mileage exceeds 600,000 kilometers.
In the passenger vehicle segment, turbocharged models now account for more than 70% of the European market. Increasingly compact engine compartment layouts are accelerating seal deterioration and core corrosion.
Air-to-air intercoolers remain the dominant product type, while air-to-water intercoolers are gaining market penetration. All-aluminum brazed construction and corrosion-resistant coatings have become industry standards.
For suppliers, key competitive advantages increasingly lie in core structural strength, welding process consistency, and platform-based application coverage.
4.5 Emerging Demand: Battery Coolers and Coolant Circuit Components
As the European electric vehicle parc continues to expand, dedicated battery thermal management components—including battery coolers, cooling plates, and heat exchangers—are expected to generate significant aftermarket demand around 2030.
The segment is currently still at an early stage, with technical standards and product specifications gradually moving toward greater harmonization.
5. Market Outlook
5.1 Stable Overall Growth, with Strong Structural Opportunities
The European automotive aftermarket is expected to maintain a compound annual growth rate (CAGR) of approximately 2%–4% between 2026 and 2030.[Note 10]
The market’s growth potential will come less from an expansion in overall vehicle volume and more from structural shifts in demand—from new vehicle supply toward aftermarket repair and maintenance, and from conventional components toward advanced thermal management systems.
5.2 Adaptive Innovation Will Become a Critical Capability
In the existing vehicle fleet, OE fitment accuracy and consistent product quality remain fundamental requirements.
In emerging growth segments, however, a strong understanding of electrified vehicle thermal management requirements and the ability to build relevant technical capabilities will become important sources of differentiation.
For suppliers, the ability to serve both the established vehicle parc and the emerging electrified vehicle market will be a key factor determining long-term competitiveness in Europe.
5.3 Localized Service Capabilities Are Becoming Increasingly Important
European customers place high expectations on supply reliability, technical documentation, and responsive after-sales service.
Suppliers capable of providing local inventory, technical support, and marketing assistance in Europe are better positioned to expand distribution channels and build long-term customer relationships.
China’s early advantages across the electrification value chain have enabled domestic automotive parts manufacturers to accumulate valuable technical experience. The next challenge for the industry is to translate these capabilities into products and services that are better aligned with local European market requirements.
For manufacturers and aftermarket suppliers, the evolution of thermal management systems represents not only a technological transition, but also a long-term market opportunity. Companies that can combine reliable coverage of the existing vehicle parc with the technical capabilities required for electrified mobility will be better positioned to capture the next stage of growth in the European aftermarket.
6. About Xintian
With thermal management systems at the core of its business strategy, Jiangxi Xintian Auto Industry Co., Ltd. is steadily strengthening its presence in the European market through a dual-product strategy that integrates the development, manufacturing, and sales of both conventional vehicle components and new energy vehicle components.
In the conventional vehicle segment, Xintian continues to expand its portfolio of radiators, condensers, and heater cores for major European vehicle applications. Supported by mature manufacturing processes and rigorous quality control systems, the company is well positioned to serve the growing replacement demand generated by Europe’s aging vehicle fleet.
In the new energy vehicle sector, Xintian is actively advancing the development of thermal management products for electric vehicle applications while systematically strengthening its technical capabilities and building long-term expertise in next-generation thermal management technologies.
At the same time, backed by the production capacity of its manufacturing facility in Chonburi, Thailand, Xintian continues to enhance its responsiveness and localized delivery capabilities for European customers. Guided by real-world operating conditions and market requirements, the company is committed to transforming product excellence into tangible service value.
The structural transformation of the European aftermarket is already underway. Through continuous investment in products, manufacturing, and service capabilities, Jiangxi Xintian Auto Industry Co., Ltd. is steadily shaping its response to the opportunities and challenges ahead, delivering reliable thermal management solutions that support the evolving needs of the European market.
Notes
[Note 1]–[Note 10]: Data referenced in this article has been compiled from ACEA publications, European automotive industry reports, McKinsey industry research, and publicly available market studies. The figures represent commonly referenced industry estimates and benchmark ranges.
📍 Jiangxi Xintian Auto Industry Co., Ltd.
🏗 No. 3,Chunyu Road, Economic and Technological Development Zone, Yichun City, Jiangxi Province, China (Postal Code: 336000)
📞 Tel: +86-795 2197226
📧 Email: info@jxxintian.com
🌐 Website: www.jxxintian.com